
Tesla Q3 2026 Earnings — Adj EPS $0.48 Beats ($0.45 Est) · Revenue $28.05B · CapEx Guide Cut $25B→$20B
Published · Updated · By Investus editorial desk (SUNRYU Partners)
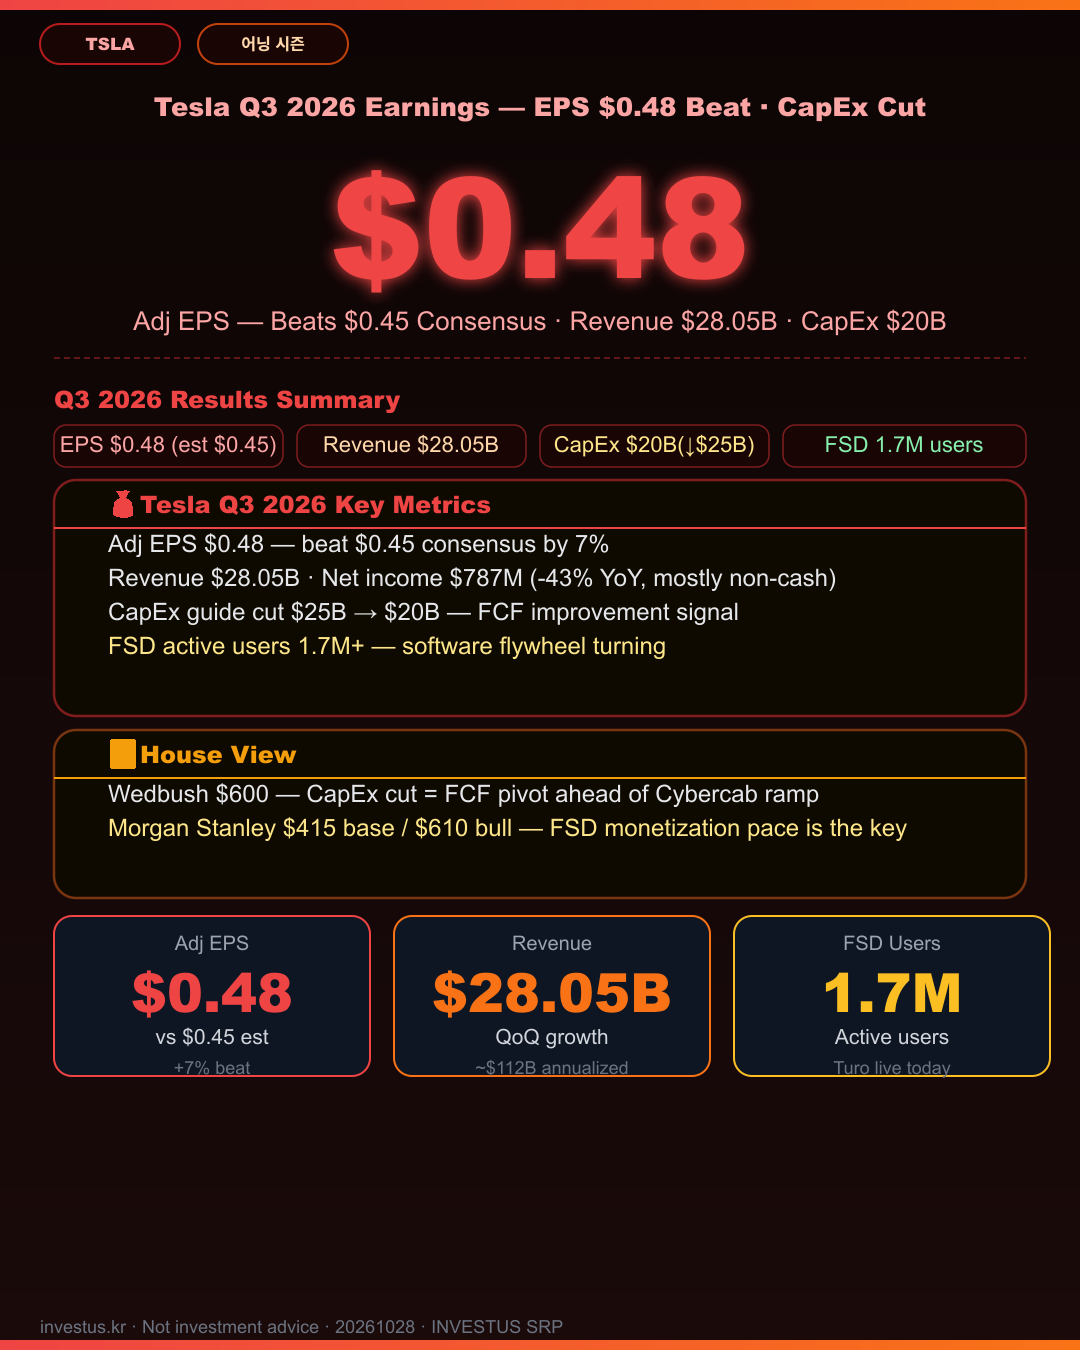
Tesla Q3 2026: Adj EPS $0.48 beat consensus $0.45 (+7%). Revenue $28.05B. Net income $787M (-43% YoY, mostly non-cash items). Energy segment revenue $4.6B (+50% YoY, record). CapEx annual guide cut from $25B to $20B. FSD active users surpassed 1.7M. FSD on Turo launches Oct 28.
What Happened
Tesla (TSLA) reported Q3 2026 results. Key metrics:
- Adjusted EPS: $0.48 (consensus $0.45, +7% beat)
- Revenue: $28.05B
- Net Income: $787M (-43% YoY — primarily non-cash items)
- Energy segment revenue: $4.6B (+50% YoY, record quarter)
- Services & Other: $3.5B (+26% YoY)
- CapEx annual guidance: $25B → $20B (cut)
- FSD active users: 1.7M+
The adjusted EPS beat surprised markets positively. Revenue of $28.05B keeps Tesla on a $100B+ annualized run rate. The net income decline reflects non-cash fair-value changes in convertible notes and derivatives — not operating deterioration.
Segment Breakdown
Automotive delivered approximately 469,000 vehicles in Q3, led by Model Y's refreshed variants gaining traction in China and Europe. Cybertruck production has stabilized around 20,000 units per quarter. ASP dipped slightly quarter-over-quarter, but rising FSD software attach rates are expanding per-vehicle software contribution.
Energy hit a record quarter. Megapack deliveries grew 50%+ year-over-year, absorbing grid-scale storage demand that has been building for two years. The Lathrop Megafactory reached full capacity in Q2 and contributed fully in Q3. Energy segment gross margins of 25–27% now exceed automotive margins — a structural shift in Tesla's profit mix.
Services & Other ($3.5B) was driven by Supercharging fees, FSD subscriptions, and software sales. FSD's 1.7M active subscribers at $99–199/month represent a $2–4B annualized recurring revenue stream.
Why CapEx Cut Matters
The $20B CapEx guidance reduction signals Tesla is shifting from expansion to efficiency. With Cybertruck in production, Cybercab launch preparation underway, and Gigafactory Texas at scale, the heaviest capital deployment phase is winding down. FCF improvement is the near-term result — opening room for buybacks or debt reduction.
Analyst Views
Wedbush (Dan Ives) maintains $600 target, calling the CapEx cut a rational move to build financial strength ahead of Cybercab and Optimus commercialization. FSD's 1.7M user count validates the software flywheel.
Morgan Stanley (Adam Jonas) holds $415 base, $610 bull. Notes the EPS beat helps investor confidence but flags non-cash volatility as a persistent earnings-quality concern. Views energy segment acceleration as a positive structural development.
Sources & further reading
Related Guides
Related articles
Project Crystal Sun: What Musk Confirmed, What Fort Bend Agreed, and What Is Still Unverified
Musk posted the project name only. Fort Bend approved four incentive agreements. Tesla has not confirmed the site, a groundbreaking, or a production date.
Tesla Cybercab and NHTSA Special Order AQ26002: What Public Investors Can Actually Read
NHTSA’s Special Order AQ26002 asked Tesla under oath how Cybercab meets federal safety standards. What is public as of early November 2026 is a confidentiality claim over the sworn answers—especially Request 8—and a first-responder plan, not a finding of noncompliance. This guide maps the docket and Tesla’s primary filings. It is not a buy, sell, or price-target note.
Tesla confirms a Vietnam launch — into a market where VinFast already holds about 36% of new cars
A Tesla recruiter said on Oct. 28, 2026 that the company is “officially coming” to Vietnam and posted five jobs, including sales manager, service manager, and charging-project developer. Tesla Motors Vietnam LLC was registered in Ho Chi Minh City on Sept. 11. VinFast has taken about 36% of Vietnam’s new-car market in the first nine months of 2026. Southeast Asia is opening; tariffs, price, and charging will decide how large the opening is.
Disclaimer
This article is editorial research for informational purposes only. It is not investment advice, a recommendation, or a solicitation to buy or sell any security, and does not guarantee any return. Markets carry risk of loss. Verify figures against the primary sources before making decisions.