
All 10 analyst houses raised Tesla targets — Cantor Fitzgerald $485 high · CLSA Underperform → Hold · GS $360 low · Average ~$436
Published · Updated · By Investus editorial desk (SUNRYU Partners)
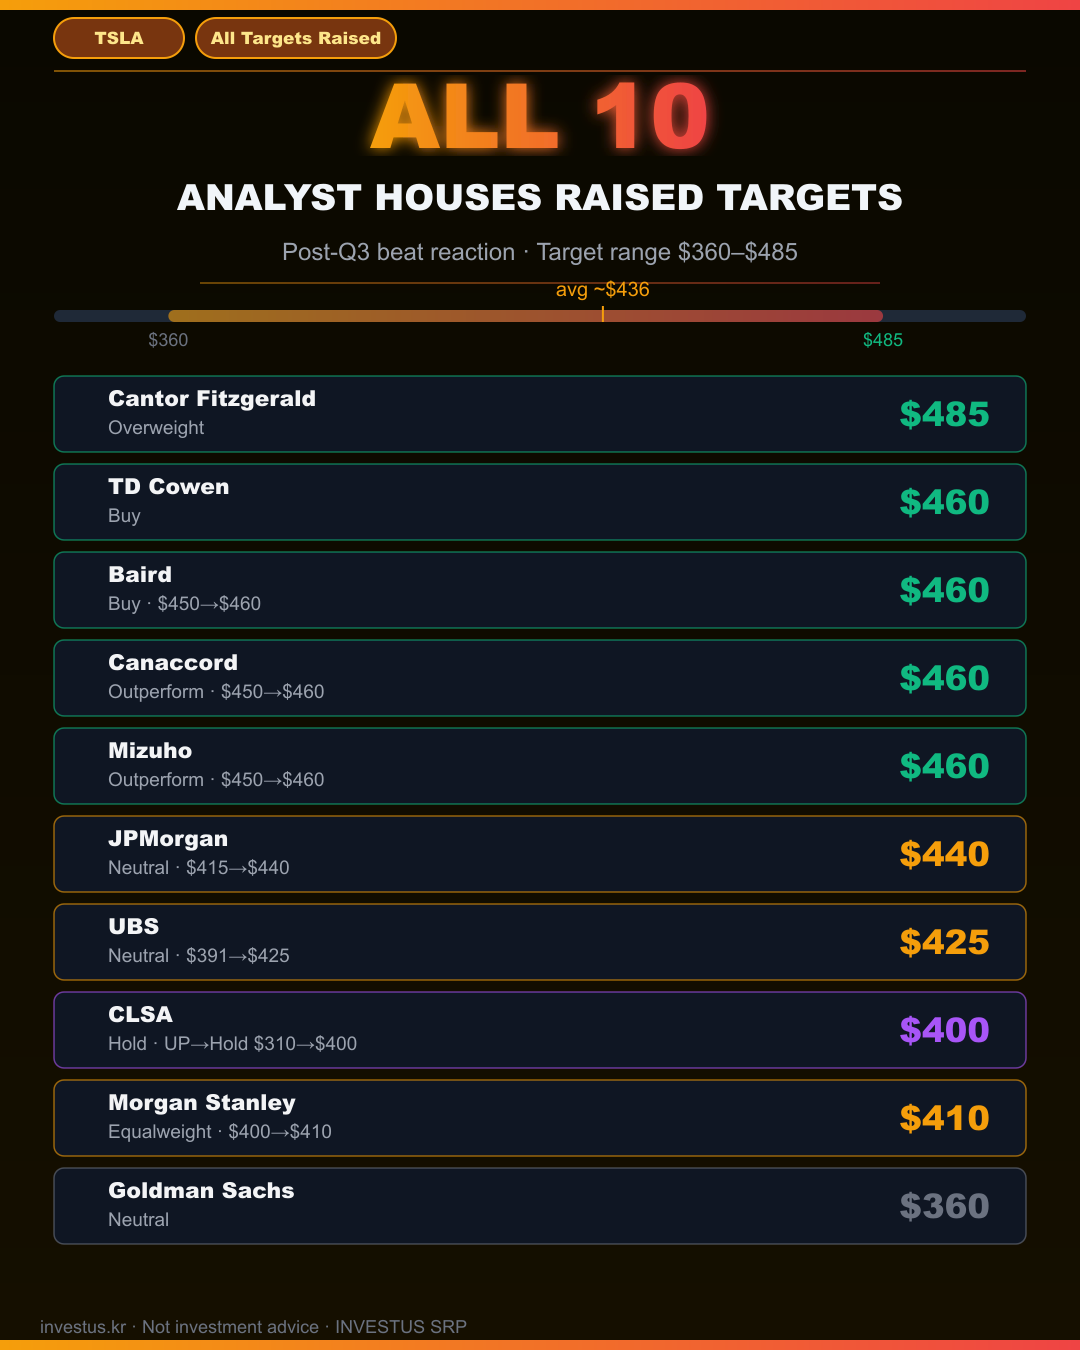
Following TSLA's Q3 2026 earnings beat, all 10 covering houses raised price targets. High: Cantor Fitzgerald $485 (Overweight). Low: Goldman Sachs $360 (Neutral). Average: ~$436. Notable: CLSA upgraded from Underperform to Hold, raising PT from $310 to $400 — the sharpest bull turn. JPMorgan: $415→$440 Neutral. Baird/Canaccord/Mizuho: all to $460 Buy/Outperform. Goldman Sachs hedge fund data shows short positions at 99th percentile — adding structural short-squeeze pressure.
What Happened
All 10 analyst houses raised TSLA price targets following Q3 2026 earnings. Full list:
- Cantor Fitzgerald (Andres Sheppard): Overweight, $485 (highest)
- TD Cowen (Ray Michaeli): Buy, $460
- Baird: Buy, $450→$460
- Canaccord (Alexander Potter): Outperform, $450→$460
- Mizuho (Vijay Rakesh): Outperform, $450→$460
- JPMorgan (Rajat Gupta): Neutral, $415→$440
- UBS (Joseph Spak): Neutral, $391→$425
- Morgan Stanley (Andrew Peretz): Equalweight, $400→$410
- CLSA (Christopher Richter): Upgraded Underperform→Hold, $310→$400 (largest single change)
- Goldman Sachs (Mark Delaney): Neutral, $360 (lowest)
Target range: $360–$485. Average: ~$436. Five Buy/Outperform/Overweight. Five Neutral/Hold/Equalweight. No Underperform or Sell ratings remain.
More Context
CLSA's upgrade from Underperform to Hold is the most significant rating change. Christopher Richter was one of the most bearish voices on TSLA — reversing to Hold with a $90 target increase signals a structural change in the bear case. The FCF beat ($2.9B vs. $1.3B est), gross margin recovery (19.6% vs. 16.8% last Q), and Cybercab traction drove the revision.
Goldman Sachs data: Hedge funds are betting against stocks at near-record levels — short sales outpaced purchases 5:1 globally, positions at the 99th percentile of the past five years. TSLA has historically been a top short target. Universal analyst upgrades combined with formal merger committee announcement structurally pressures the short thesis.
Key View
Five Buy/Outperform ratings at $460–$485 vs. Goldman's $360 Neutral reflects genuine disagreement on Robotaxi timeline. AJ Investment Research: TSLA trades at 416× trailing LTM earnings — the most expensive large-cap globally. The premium is justified by the FCF + Cybercab + Optimus + merger optionality thesis. Goldman ($360) remains most skeptical on autonomy commercialization timing.
Sources & further reading
See the body and ticker IR links for sources on this note.
Related Guides
Related articles
Anthropic's $120.5B SpaceX Compute Deal: What the 90-Day Exit Clause Means After the 'Mid-2027' Report
Anthropic's S-1/A caps SpaceX compute at $120.5B with a 90-day exit after early 2027. What the 'mid-2027' report adds and what remains unconfirmed.
35,578 Open Grok Build Apps: What Claroc Measured and What SpaceXSI Disputes
SpaceXSI's Grok Build: Claroc says 35,578 published apps opened with no sign-in. What was measured, what SpaceXSI disputes, and open questions.
Starship Flight 15 Explained: SpaceX's First Attempt to Catch Both Stages, What Is Confirmed and What Investors Should Watch
SpaceX says Starship Flight 15 is preparing to launch as soon as Friday, November 13, 2026, pending regulatory approval, on the first plan to catch both Super Heavy and the Starship upper stage. The 75-minute window opens at 4:45 p.m. CT. This note separates confirmed facts, company plans, secondary reports, and open questions. It is not a buy, a sell, or a share-price call.
Disclaimer
This article is editorial research for informational purposes only. It is not investment advice, a recommendation, or a solicitation to buy or sell any security, and does not guarantee any return. Markets carry risk of loss. Verify figures against the primary sources before making decisions.