
NVDA — Commerce Dept OKs China AI Chip Sales, Including Sanctioned Firms
Published · Updated · By Investus editorial desk (SUNRYU Partners)
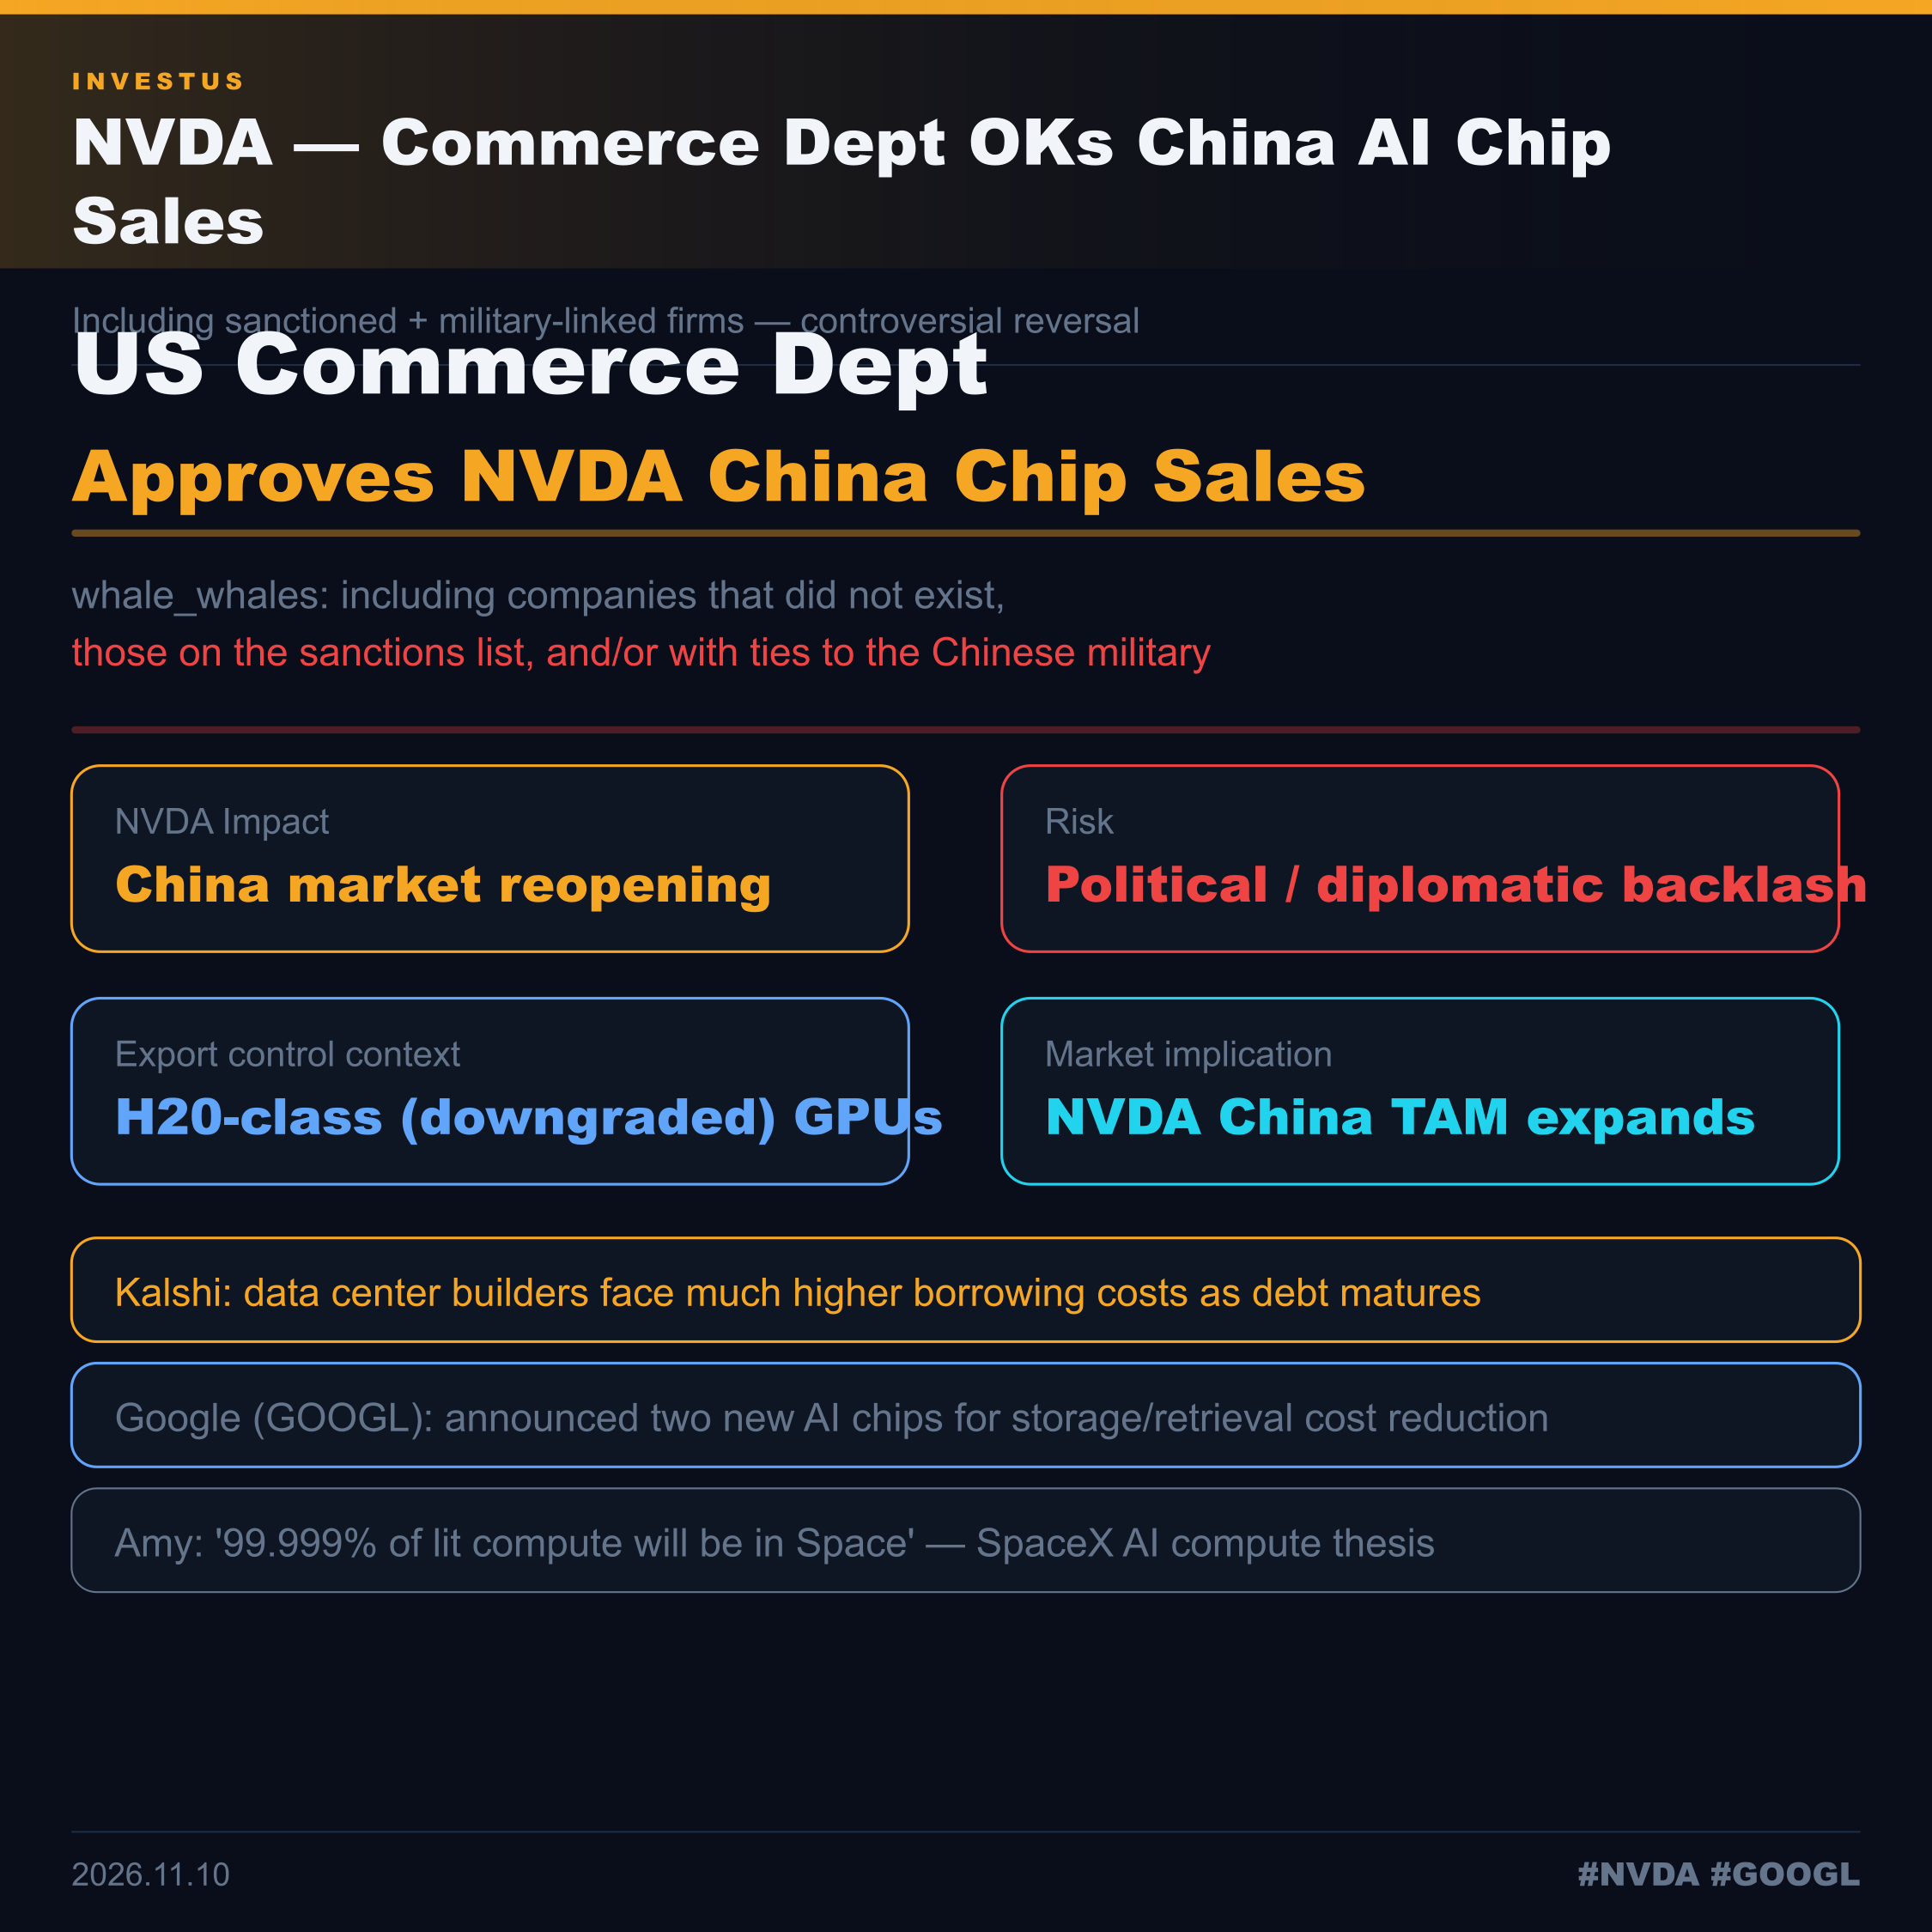
The US Commerce Department has reportedly been approving NVIDIA GPU and chip sales to Chinese companies including those that did not exist on paper, those on the sanctions list, and those with ties to the Chinese military. The paradoxical reversal could be a short-term NVDA catalyst but carries political and diplomatic backlash risk.
What happened
Whale_whales reported that the US Commerce Department has been approving NVIDIA GPU and chip sales to Chinese companies — including firms that did not previously exist in filings, entities on the US export sanctions list, and companies with ties to the Chinese military.
This is highly unusual. Since 2022, the US has progressively tightened AI chip export restrictions to China — first banning H100 and A100, then Chinese-market downgraded variants like H800 and A800, then tightening H20 licensing requirements. This report, if accurate, describes a reversal: the Commerce Department granting licenses contrary to those escalating restrictions.
More detail
Several explanations are possible. First, the approved chips may be H20-class or below — the US government typically applies strict controls only to leading-edge chips and exercises commercial discretion on lower tiers. Second, approvals may carry end-user certificate conditions. Third, this could reflect a policy shift tied to US–China diplomatic conditions.
The paradox of approvals for sanctioned and military-linked entities makes this more than a standard tier-based decision. It likely involves political-level judgment and could face Congressional or national-security community pushback.
Separately, Kalshi Finance reported that AI data-center builders are facing much higher borrowing costs as large debt balances come due — adding financial pressure context to the China chip story, as NVDA's China TAM expansion opportunity sits within a more complex financing backdrop for hyperscale infrastructure.
Analyst and house views
Susquehanna maintained bullish views on NVDA ahead of the November 17 earnings release, citing intact AI demand. China market re-entry potential represents additional upside but is too regulatory-uncertain to be reflected in guidance. NVDA's current P/E of 22.9× compares to a 10-year average of 61.2× — the deepest historical discount in years.
investus Research
Sources & further reading
Related Guides
Related articles
Daily Snapshot 2026.07.15 — IBM Earnings Shock + Top 9
BREAKING IBM Q2 miss −28% · CPI −0.4% · Chamath TSLA~$600 · Robotaxi 765 · GOOGL 1.6GW · TSMC $140B · JPM $16.9B · NFLX $169 · SNDK $3,100 · LCID −41.74%. More in individual reports.
Anthropic's $120.5B SpaceX Compute Deal: What the 90-Day Exit Clause Means After the 'Mid-2027' Report
Anthropic's S-1/A caps SpaceX compute at $120.5B with a 90-day exit after early 2027. What the 'mid-2027' report adds and what remains unconfirmed.
35,578 Open Grok Build Apps: What Claroc Measured and What SpaceXSI Disputes
SpaceXSI's Grok Build: Claroc says 35,578 published apps opened with no sign-in. What was measured, what SpaceXSI disputes, and open questions.
Disclaimer
This article is editorial research for informational purposes only. It is not investment advice, a recommendation, or a solicitation to buy or sell any security, and does not guarantee any return. Markets carry risk of loss. Verify figures against the primary sources before making decisions.