
Micron Deep Dive — Data Center +651% · Fair Value $1,520 · 25% Undervalued
Published · Updated · By Investus editorial desk (SUNRYU Partners)
Based on Q2 2026 results, Micron's data center revenue surged +651% YoY. FCF +951%, net cash $23B, and reverse DCF fair value of $1,520 implies 25% upside from current price.
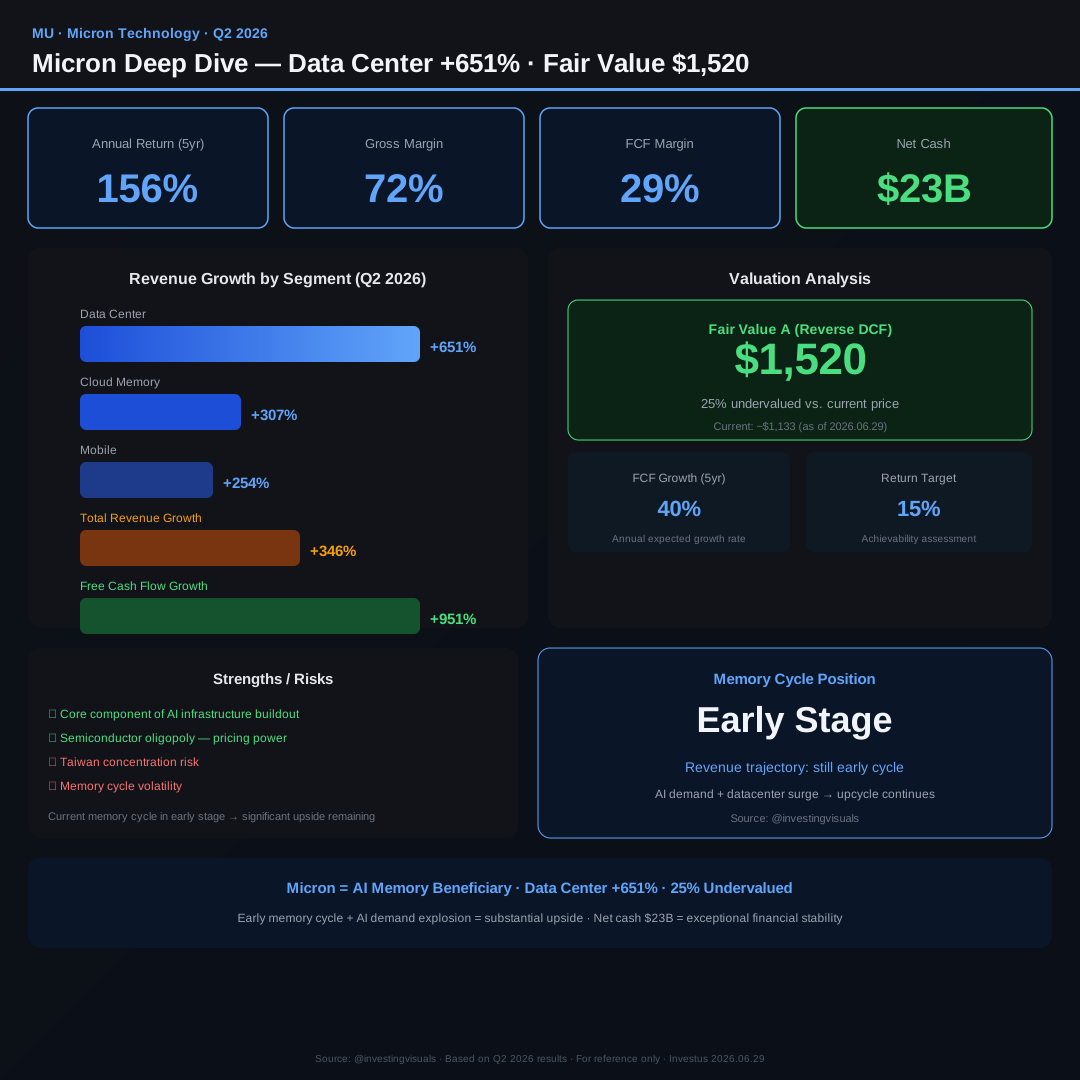
Key Metrics Summary
• Annual return (5yr): 156%
• Gross margin: 72%
• FCF margin: 29%
• Net cash: $23B
Revenue Growth by Segment (Q2 2026)
• Data Center: +651%
• Cloud Memory: +307%
• Mobile: +254%
• Total revenue growth: +346%
• Free cash flow growth: +951%
Valuation Analysis
• Reverse DCF fair value: $1,520
• Current price: ~$1,133 (as of 2026.06.29)
• Undervaluation: 25%
• FCF 5yr expected growth: 40% p.a.
• 15% annual return achievability: high
Strengths
• Core component supplier for AI infrastructure buildout
• Semiconductor oligopoly → pricing power
• Net cash $23B = exceptional financial stability
Risks
• Taiwan concentration risk (geopolitical)
• Memory cycle volatility
Memory Cycle Position
Currently early in memory cycle → significant upside remaining
AI demand + datacenter surge → upcycle expected to continue
Sources & further reading
See the body and ticker IR links for sources on this note.
Related Guides
Related articles
Anthropic's $120.5B SpaceX Compute Deal: What the 90-Day Exit Clause Means After the 'Mid-2027' Report
Anthropic's S-1/A caps SpaceX compute at $120.5B with a 90-day exit after early 2027. What the 'mid-2027' report adds and what remains unconfirmed.
35,578 Open Grok Build Apps: What Claroc Measured and What SpaceXSI Disputes
SpaceXSI's Grok Build: Claroc says 35,578 published apps opened with no sign-in. What was measured, what SpaceXSI disputes, and open questions.
Starship Flight 15 Explained: SpaceX's First Attempt to Catch Both Stages, What Is Confirmed and What Investors Should Watch
SpaceX says Starship Flight 15 is preparing to launch as soon as Friday, November 13, 2026, pending regulatory approval, on the first plan to catch both Super Heavy and the Starship upper stage. The 75-minute window opens at 4:45 p.m. CT. This note separates confirmed facts, company plans, secondary reports, and open questions. It is not a buy, a sell, or a share-price call.
Disclaimer
This article is editorial research for informational purposes only. It is not investment advice, a recommendation, or a solicitation to buy or sell any security, and does not guarantee any return. Markets carry risk of loss. Verify figures against the primary sources before making decisions.