
Daily Summary 2026-10-29 — MSFT·GOOGL Earnings · TSLA Cybercab 573 · AWS 3x · FOMC Restructure
Published · Updated · By Investus editorial desk (SUNRYU Partners)
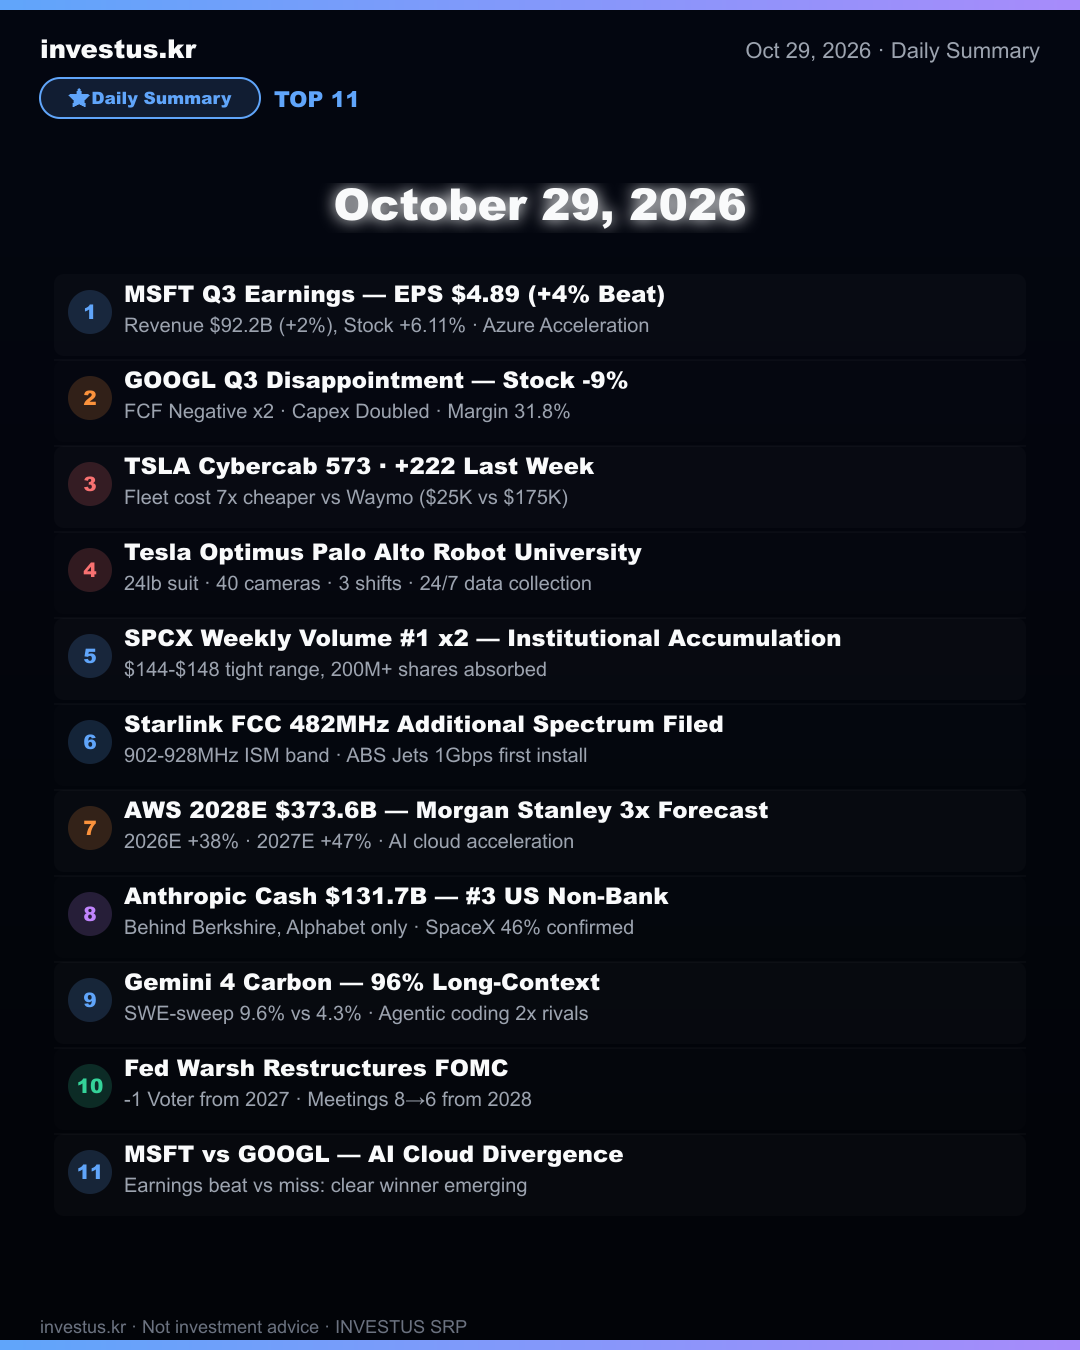
MSFT Q3 EPS $4.89 (+4% beat), Revenue $92.2B (+2% beat), +6.11%. GOOGL Q3 revenue inline but -9%: margin 31.8%, 2nd straight negative FCF, capex doubled. TSLA Cybercab 573 (+222 last week), 7x cheaper than Waymo. AWS 2028E $373.6B (Morgan Stanley, ~3x 2025). Anthropic cash $131.7B = #3 non-bank US company. Gemini 4 Carbon 96% long-context. Fed Warsh: -1 voter 2027, meetings 8→6 in 2028.
The Big Picture
Microsoft (MSFT) reported Q3 FY2027 earnings with EPS $4.89 (est. $4.72, +4% beat) and revenue $92.2B (est. $90.7B, +2% beat), sending shares +6.11%. With EPS +18% YoY and revenue +19% YoY, the AI demand cycle is continuing to convert into real earnings.
Alphabet (GOOGL) matched revenue estimates at $127.6B (+25% YoY) but dropped -9% on multiple disappointments: Search ad revenue $63.4B missed by -2%, operating margin compressed from 34% to 31.8%, free cash flow was negative for the second straight quarter (-$5.9B in Q2, -$9.1B in Q3), and CapEx doubled year-over-year.
Tesla Cybercab registrations in Texas updated to 573 total units, with +222 added in the past week alone. The per-unit cost is approximately $25,000 — one-seventh of Waymo's $175,000 per vehicle.
Morgan Stanley projects AWS revenue to nearly triple by 2028 to $373.6B. Anthropic's S-1 reveals $131.7B in cash and investments, ranking #3 among all non-banking US companies. Google unveiled Gemini 4 Carbon (96% long-context score), SpaceX filed with the FCC to add 482 MHz of Starlink satellite-to-phone spectrum, and Fed Chair Warsh announced FOMC restructuring: -1 voting member from 2027, meetings cut 8→6 in 2028.
MSFT Earnings Deep Dive
Azure Cloud was the star of Microsoft's quarter, growing +33% YoY as AI workloads drive infrastructure demand. Copilot AI subscriptions are showing rapid enterprise adoption and driving ARPU expansion across the Office 365 base, directly improving software segment margins.
Microsoft's quarter is significant because it is the first large-scale proof that the AI investment cycle is translating into earnings growth. CapEx is rising, but revenue growth is outpacing cost growth — operating margin held or improved slightly quarter-over-quarter. This is the profit inflection signal the market had been waiting for.
GOOGL Earnings Deep Dive
Alphabet's -9% drop reflects compounding disappointments. Google Cloud beat at $30.7B (+5% vs estimates), but core Search ads at $63.4B came in -2% below consensus. The market read this as early evidence of AI-search cannibalization — Google's own AI tools reducing traditional Search ad clicks and challenging the core revenue model.
The two-quarter streak of negative FCF (-$5.9B Q2, -$9.1B Q3) matters because it confirms Google is still deep in investment mode. While MSFT has achieved profit inflection, GOOGL may need 1-2 more quarters before CapEx-to-revenue crossover. This gap is the core reason behind the divergence in the two stocks' performance.
Tesla Cybercab Cost Advantage Confirmed
The 573-unit DMV registration matters more for unit economics than raw count. At $25,000 per vehicle versus Waymo's $175,000, Tesla has a 7× hardware cost advantage. This means Tesla can deploy 7 Cybercabs for every one Waymo vehicle at the same capital outlay — a structural advantage for network scaling and profitability timing.
Tesla's cost structure is designed to get cheaper at scale. Cybercab shares components with existing Tesla vehicles produced at Gigafactory Texas. The FSD AI development cost is a one-time fixed cost: each additional Cybercab adds near-zero marginal AI cost, while Waymo's LiDAR + radar + camera sensor suite keeps per-vehicle hardware costs elevated regardless of scale.
Investment Takeaways
Today's earnings split MSFT (profit inflection confirmed) from GOOGL (still in investment phase) with unusual clarity. Tesla Cybercab's cost advantage is now backed by real registration data, and Anthropic's $131.7B cash pile publicly confirms the AI compute demand chain through its S-1 filing.
Portfolio framing: MSFT has the earnings evidence to support multiple expansion as an AI growth stock. GOOGL needs 1-2 more quarters of data — watch Cloud growth rate against Search cannibalization. TSLA's Cybercab cost thesis is now data-backed; fleet expansion pace is the next price catalyst. AWS 3x growth by 2028 and FOMC structural changes add further macro context to position sizing.
Sources & further reading
Related Guides
Related articles
Anthropic's $120.5B SpaceX Compute Deal: What the 90-Day Exit Clause Means After the 'Mid-2027' Report
Anthropic's S-1/A caps SpaceX compute at $120.5B with a 90-day exit after early 2027. What the 'mid-2027' report adds and what remains unconfirmed.
35,578 Open Grok Build Apps: What Claroc Measured and What SpaceXSI Disputes
SpaceXSI's Grok Build: Claroc says 35,578 published apps opened with no sign-in. What was measured, what SpaceXSI disputes, and open questions.
Starship Flight 15 Explained: SpaceX's First Attempt to Catch Both Stages, What Is Confirmed and What Investors Should Watch
SpaceX says Starship Flight 15 is preparing to launch as soon as Friday, November 13, 2026, pending regulatory approval, on the first plan to catch both Super Heavy and the Starship upper stage. The 75-minute window opens at 4:45 p.m. CT. This note separates confirmed facts, company plans, secondary reports, and open questions. It is not a buy, a sell, or a share-price call.
Disclaimer
This article is editorial research for informational purposes only. It is not investment advice, a recommendation, or a solicitation to buy or sell any security, and does not guarantee any return. Markets carry risk of loss. Verify figures against the primary sources before making decisions.