
TSLA FSD Subscribers Hit 1.29M (+17% QoQ) — July 22 Q2 Record Earnings Expected
Published · Updated · By Investus editorial desk (SUNRYU Partners)
Tesla FSD active subscribers reached 1.29M in Q1 2026, up +17% from 1.10M in Q4 2025. SPCX target raised $190→$230. Q2 earnings July 22, est. revenue $39,098M. 'Best earnings in years' forecast.
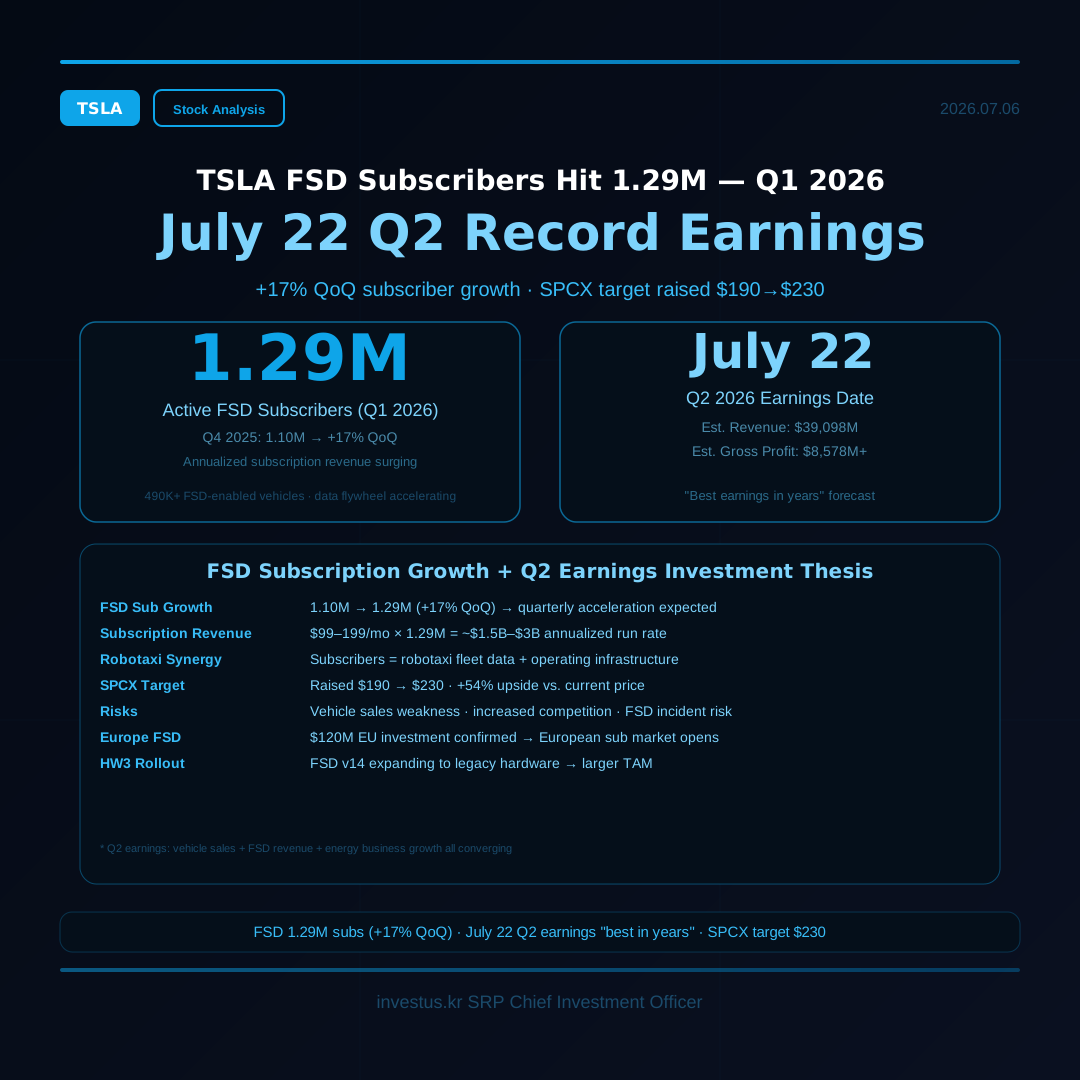
FSD Subscription Status
• Q1 2026: 1.29M active subscribers
• Q4 2025: 1.10M → +17% QoQ
• Monthly fee: $99–$199
• Annualized run rate: ~$1.5B–$3B
Why 1.29M Subscribers Matters
FSD subscribers are not just a software sales metric. They represent the clearest evidence that Tesla's business model is transitioning from hardware (vehicle sales) to software and services — a structurally higher-margin, recurring revenue stream.
At $99/month × 1.29M subscribers, the annualized run rate is $1.53B. At $199/month, it reaches $3.08B annually. FSD subscriptions alone can contribute multiple billions to Tesla's annual operating income. More importantly, the +17% QoQ growth rate — if maintained — puts Tesla on track to surpass 2M active subscribers before 2027.
FSD v14 HW3 Rollout Expands TAM
FSD v14 deploying to HW3 hardware vehicles materially expands the addressable subscriber base. HW3 is the FSD computer installed in Model 3/Y/S/X vehicles shipped from 2019 through 2022 — the majority of Tesla vehicles on the road globally. This single deployment decision adds potentially millions of new FSD-eligible vehicles to the subscription funnel.
The Europe FSD launch is the other major TAM expansion lever. Europe accounts for 300,000–400,000 Tesla deliveries per year. With FSD subscriptions now opening in that market, the subscriber base could add hundreds of thousands of new users.
The Robotaxi Data Flywheel
Every FSD subscriber driving contributes real-world miles to Tesla's training dataset. More data → better FSD → more subscribers → more data. By July 2026, Tesla's cumulative FSD miles exceed tens of billions. Competitors collecting millions of miles are operating at a fraction of this scale — and the gap is compounding.
Q2 2026 Earnings (July 22)
• Est. Revenue: $39,098M
• Est. Gross Profit: $8,578M+
• Outlook: 'Best earnings in years'
The Q2 2026 "best earnings in years" expectation rests on three simultaneous tailwinds: FSD subscription growth, Lathrop Megafactory reaching full capacity (energy segment), and robotaxi service revenue beginning to register. The business mix is shifting — software/services/energy are offsetting auto margin pressure.
SPCX Target Raised $190 → $230
The SPCX target hike reflects Starlink's 92M subscribers, the NASA and Space Force contract wins, and the Anthropic computing contract pipeline. Like FSD, Starlink is a recurring subscription model — with 92M subscribers generating billions in annualized revenue and growing.
Sources & further reading
Related Guides
Related articles
Project Crystal Sun: What Musk Confirmed, What Fort Bend Agreed, and What Is Still Unverified
Musk posted the project name only. Fort Bend approved four incentive agreements. Tesla has not confirmed the site, a groundbreaking, or a production date.
Tesla Cybercab and NHTSA Special Order AQ26002: What Public Investors Can Actually Read
NHTSA’s Special Order AQ26002 asked Tesla under oath how Cybercab meets federal safety standards. What is public as of early November 2026 is a confidentiality claim over the sworn answers—especially Request 8—and a first-responder plan, not a finding of noncompliance. This guide maps the docket and Tesla’s primary filings. It is not a buy, sell, or price-target note.
Tesla confirms a Vietnam launch — into a market where VinFast already holds about 36% of new cars
A Tesla recruiter said on Oct. 28, 2026 that the company is “officially coming” to Vietnam and posted five jobs, including sales manager, service manager, and charging-project developer. Tesla Motors Vietnam LLC was registered in Ho Chi Minh City on Sept. 11. VinFast has taken about 36% of Vietnam’s new-car market in the first nine months of 2026. Southeast Asia is opening; tariffs, price, and charging will decide how large the opening is.
Disclaimer
This article is editorial research for informational purposes only. It is not investment advice, a recommendation, or a solicitation to buy or sell any security, and does not guarantee any return. Markets carry risk of loss. Verify figures against the primary sources before making decisions.