
Tesla Q3 gross margin 19.6% — recovery from Q2 16.8% (+2.8pp) · Trailing 12M revenue $100B+ for 2nd straight quarter · Services gross profit $724M all-time record
Published · Updated · By Investus editorial desk (SUNRYU Partners)
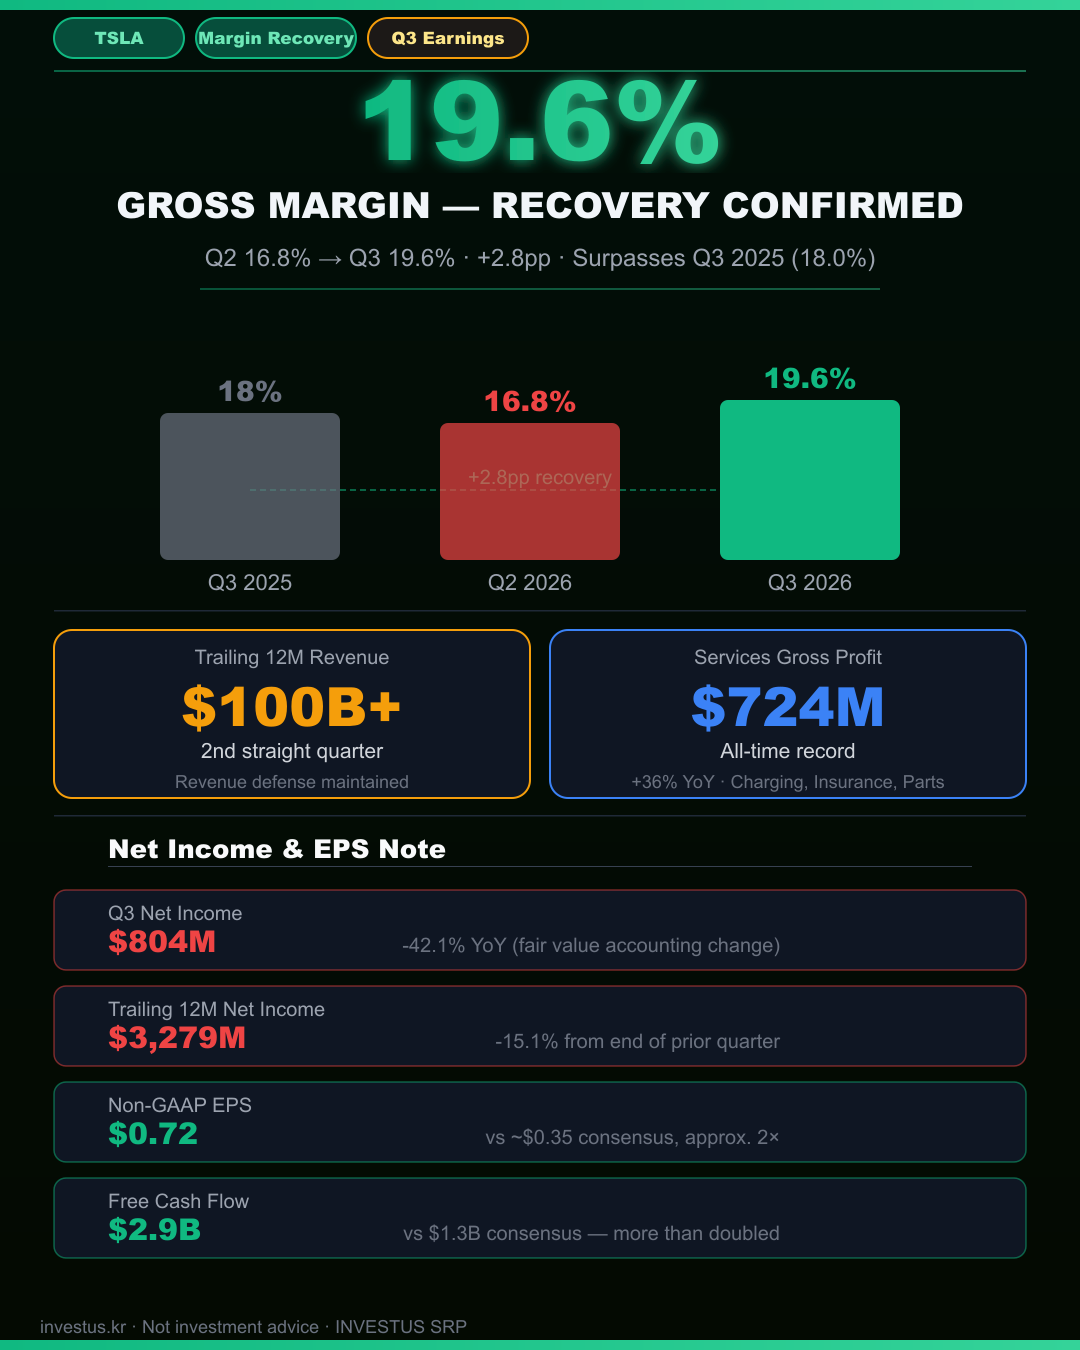
Tesla Q3 2026 gross margin came in at 19.6%, up 2.8pp from Q2 2026's 16.8% and above Q3 2025's 18.0% — confirming a recovery trend. Trailing 12-month revenue topped $100B for the second consecutive quarter. Services & Other gross profit hit $724M, an all-time record, with service revenue +33% YoY. Net income was $804M (-42.1% YoY) due to fair value accounting changes; Non-GAAP EPS of $0.72 was ~2× consensus. FCF was $2.9B vs. $1.3B estimate.
What Happened
Tesla Q3 2026 gross margin: 19.6%. Q2 2026: 16.8%. Q3 2025: 18.0%. The recovery is confirmed — Q3 beats both prior quarter and prior year. Trailing 12-month revenue exceeded $100B for the second consecutive quarter, solidifying Tesla as a stable $100B+ annual revenue company.
Services & Other gross profit: $724M — all-time record. Service revenue: +33% YoY, driven by Supercharging (now open to other brands), insurance (FSD-data-driven competitive advantage), and parts sales (scaling with 10M+ cumulative fleet).
Q3 net income: $804M (-42.1% YoY). Trailing 12M: $3,279M (-15.1% QoQ). These declines are substantially driven by fair value accounting changes on non-public equity holdings (SpaceX, X, etc.). Non-GAAP EPS: $0.72 vs ~$0.35 consensus — approximately 2×. FCF: $2.9B vs $1.3B estimate — more than doubled.
More Context
Q2 2026's 16.8% gross margin was the trough — driven by price reductions, new model ramp costs, and energy segment margin compression. The Q3 recovery to 19.6% reflects: improved vehicle cost structure, better mix, and services segment contribution. The path toward 25%+ target margin likely set its low point in Q2.
The $724M services gross profit is structural, not one-time. Tesla's Supercharger network now serves multi-brand customers. Insurance leverages FSD safety data for a structural cost advantage. Parts/accessories scale linearly with the 10M+ cumulative fleet.
Key View
Wolf Financial: 'TSLA has topped $100B in trailing 12-month revenue for the second straight quarter. Gross margin climbed to 19.6% in Q3, up from 16.8% last quarter and 18.0% a year ago.' Wedbush: gross margin recovery is the primary EPS upside driver for 2026–2028; services growth buffers vehicle margin volatility. Continuation into Q4 would support further estimate revisions upward.
Sources & further reading
See the body and ticker IR links for sources on this note.
Related Guides
Related articles
Anthropic's $120.5B SpaceX Compute Deal: What the 90-Day Exit Clause Means After the 'Mid-2027' Report
Anthropic's S-1/A caps SpaceX compute at $120.5B with a 90-day exit after early 2027. What the 'mid-2027' report adds and what remains unconfirmed.
35,578 Open Grok Build Apps: What Claroc Measured and What SpaceXSI Disputes
SpaceXSI's Grok Build: Claroc says 35,578 published apps opened with no sign-in. What was measured, what SpaceXSI disputes, and open questions.
Starship Flight 15 Explained: SpaceX's First Attempt to Catch Both Stages, What Is Confirmed and What Investors Should Watch
SpaceX says Starship Flight 15 is preparing to launch as soon as Friday, November 13, 2026, pending regulatory approval, on the first plan to catch both Super Heavy and the Starship upper stage. The 75-minute window opens at 4:45 p.m. CT. This note separates confirmed facts, company plans, secondary reports, and open questions. It is not a buy, a sell, or a share-price call.
Disclaimer
This article is editorial research for informational purposes only. It is not investment advice, a recommendation, or a solicitation to buy or sell any security, and does not guarantee any return. Markets carry risk of loss. Verify figures against the primary sources before making decisions.