
Reuters exclusive: 3 TSLA-SPCX merger structures — SPCX acquires TSLA / New holdco / All-stock swap · Apollo & Goldman Sachs 8.3% deal financing
Published · Updated · By Investus editorial desk (SUNRYU Partners)
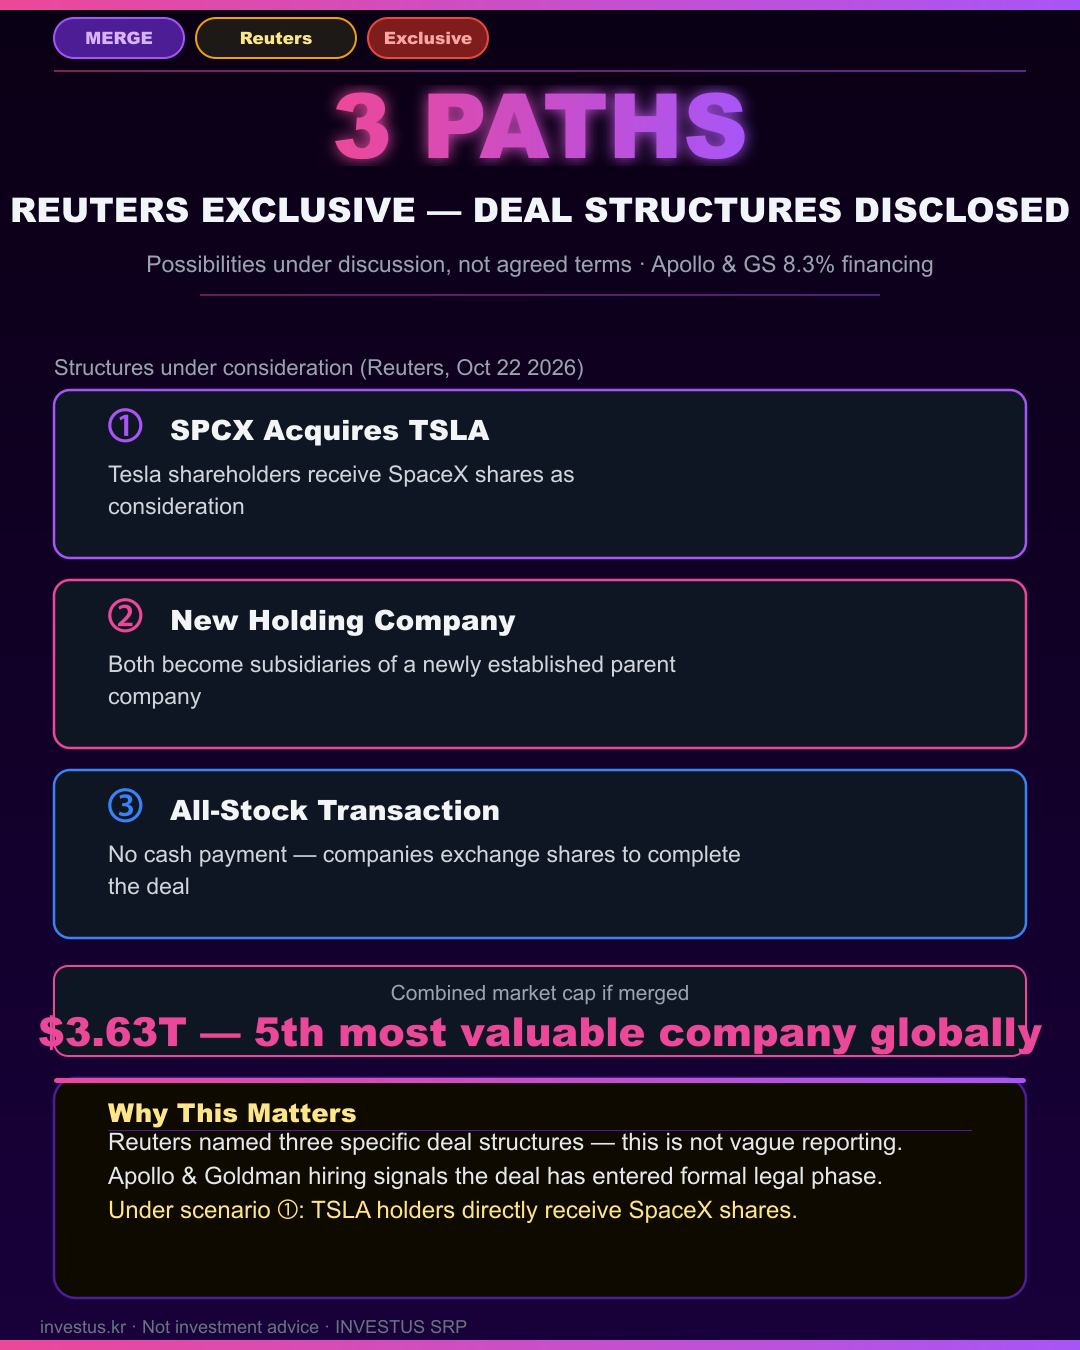
Reuters exclusively reported three TSLA-SPCX deal structures under consideration: ① SPCX acquires TSLA (Tesla shareholders receive SpaceX stock); ② Both become subsidiaries of a new holding company; ③ All-stock transaction (no cash). Apollo and Goldman Sachs are reportedly preparing to underwrite SpaceX lower-rated debt at ~8.3% (Semafor). Combined market cap: ~$3.63T (SPCX $2.10T + TSLA $1.53T), 5th globally.
What Happened
Reuters exclusively reported the specific deal structures being explored for the TSLA-SPCX merger. SpaceX has approached Tesla in recent months; advisors have been hired on both sides. Three structures under consideration: ① SPCX acquires TSLA: Tesla shareholders receive SpaceX stock as consideration — TSLA holders become SpaceX shareholders directly. ② New holding company: both companies become subsidiaries of a new parent, maintaining separate legal entities. ③ All-stock transaction: no cash, companies exchange shares to complete the deal. Reuters noted: 'These are possibilities being discussed, not agreed terms.'
Apollo and Goldman Sachs are reportedly preparing to underwrite SpaceX lower-rated debt at approximately 8.3% (Semafor). Financing advisor appointment signals the deal has moved past exploratory discussion. Combined: SPCX $2.10T + TSLA $1.53T = $3.63T — 5th globally (behind Nvidia $5.36T, Apple $5.02T, Alphabet $4.09T, Microsoft $3.96T).
More Context
Funding advisor appointment by Apollo and Goldman is a material M&A procedural step. The 8.3% rate is appropriate for SpaceX's credit profile at this scale — standard for a large-cap M&A financing. Under structure ①, TSLA shareholders become SpaceX shareholders immediately — this is the basis for Kevin O'Leary's statement: 'If you own Tesla you'll own the new company.'
Structure ②: Separate operating entities under a holdco allows flexible regulatory treatment across aerospace (SpaceX), automotive (Tesla), and energy segments. Structure ③ (all-stock): the most tax-efficient path, no cash outflow needed.
Key View
Gene Munster (Deepwater Asset Management): 'This is the most synergistic merger I've ever analyzed.' Reuters reporting specific structures and advisor names signals the deal graduated from rumor to formal legal process. Barclays previously estimated a combined entity valuation of $16.8T at full synergy realization. Public Reuters reporting means the deal is concrete enough to withstand scrutiny.
Sources & further reading
See the body and ticker IR links for sources on this note.
Related Guides
Related articles
Anthropic's $120.5B SpaceX Compute Deal: What the 90-Day Exit Clause Means After the 'Mid-2027' Report
Anthropic's S-1/A caps SpaceX compute at $120.5B with a 90-day exit after early 2027. What the 'mid-2027' report adds and what remains unconfirmed.
35,578 Open Grok Build Apps: What Claroc Measured and What SpaceXSI Disputes
SpaceXSI's Grok Build: Claroc says 35,578 published apps opened with no sign-in. What was measured, what SpaceXSI disputes, and open questions.
Starship Flight 15 Explained: SpaceX's First Attempt to Catch Both Stages, What Is Confirmed and What Investors Should Watch
SpaceX says Starship Flight 15 is preparing to launch as soon as Friday, November 13, 2026, pending regulatory approval, on the first plan to catch both Super Heavy and the Starship upper stage. The 75-minute window opens at 4:45 p.m. CT. This note separates confirmed facts, company plans, secondary reports, and open questions. It is not a buy, a sell, or a share-price call.
Disclaimer
This article is editorial research for informational purposes only. It is not investment advice, a recommendation, or a solicitation to buy or sell any security, and does not guarantee any return. Markets carry risk of loss. Verify figures against the primary sources before making decisions.