
Tesla Cybercab 30K Fleet — $4.4B Revenue, $914M EBITDA Projected
Published · Updated · By Investus editorial desk (SUNRYU Partners)
Based on Morgan Stanley analysis, a 30,000 Cybercab fleet projects: ~$4.4B annual revenue and ~$914M EBITDA. Zero driver labor cost creates decisive cost advantage over conventional taxis.
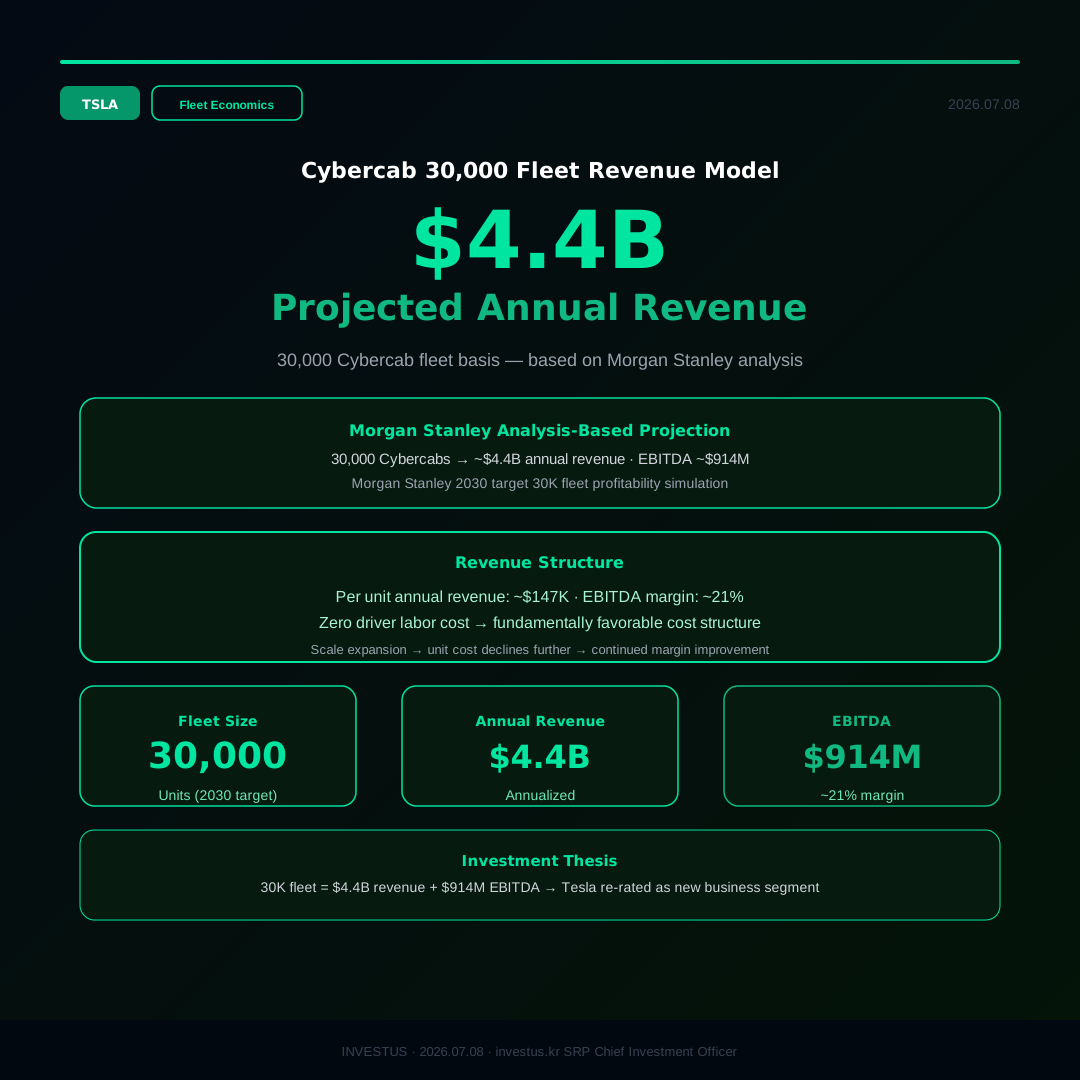
Revenue Model Projection (Based on Morgan Stanley Analysis)
Basis:
• Fleet size: 30,000 units (Morgan Stanley 2030 target)
• Analysis: MS unit Robotaxi revenue data applied
Projected Results:
• Annual Revenue: ~$4.4B
• Annual EBITDA: ~$914M
• EBITDA Margin: ~21%
Cost Structure Advantage
• Driver labor: $0 (autonomous driving)
• Remote monitoring: Minimized
• Giga Texas mass production → vehicle cost reduction
• Software updates continuously improve performance
Comparison vs Legacy Taxis
• Uber/Lyft: Driver commission 60-70%
• Waymo: LiDAR high cost + remote monitoring
• Cybercab: Hardware+electricity only → differentiated margin structure
Investment Thesis
• 30K fleet achieves $4.4B new revenue + $914M EBITDA
• Entirely new high-margin business unit added to Tesla
• Valuation re-rating warranted
Sources & further reading
Related Guides
Related articles
Project Crystal Sun: What Musk Confirmed, What Fort Bend Agreed, and What Is Still Unverified
Musk posted the project name only. Fort Bend approved four incentive agreements. Tesla has not confirmed the site, a groundbreaking, or a production date.
Tesla Cybercab and NHTSA Special Order AQ26002: What Public Investors Can Actually Read
NHTSA’s Special Order AQ26002 asked Tesla under oath how Cybercab meets federal safety standards. What is public as of early November 2026 is a confidentiality claim over the sworn answers—especially Request 8—and a first-responder plan, not a finding of noncompliance. This guide maps the docket and Tesla’s primary filings. It is not a buy, sell, or price-target note.
Tesla confirms a Vietnam launch — into a market where VinFast already holds about 36% of new cars
A Tesla recruiter said on Oct. 28, 2026 that the company is “officially coming” to Vietnam and posted five jobs, including sales manager, service manager, and charging-project developer. Tesla Motors Vietnam LLC was registered in Ho Chi Minh City on Sept. 11. VinFast has taken about 36% of Vietnam’s new-car market in the first nine months of 2026. Southeast Asia is opening; tariffs, price, and charging will decide how large the opening is.
Disclaimer
This article is editorial research for informational purposes only. It is not investment advice, a recommendation, or a solicitation to buy or sell any security, and does not guarantee any return. Markets carry risk of loss. Verify figures against the primary sources before making decisions.